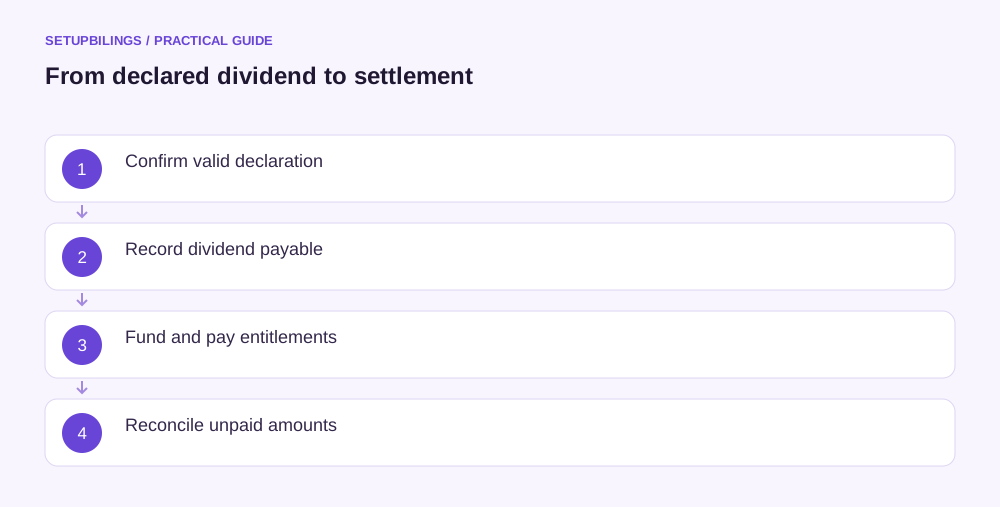
When a company validly declares a dividend and a present obligation arises, record the distribution against the appropriate retained-earnings or distribution account and credit Dividend payable. Later payment clears that liability. A dividend is a distribution to shareholders, so it should not be treated as an ordinary operating expense or confused with a director’s personal withdrawal.
Establish that declaration has occurred
A proposal or recommendation is different from a valid declaration. Review the resolutions, authority, shareholder entitlement and effective date under the applicable company requirements.
Section 123 of the Companies Act addresses permitted sources and conditions for dividends, including depreciation-related requirements and a separate scheduled-bank account for the declared amount. The bookkeeping journal does not itself establish that those conditions have been satisfied.
Use the approved dividend working and shareholder register. The declared total should reconcile to eligible shares and the supported amount per share or other applicable entitlement basis.
Illustrative declaration
Assume an Indian private company validly declares a supported ₹1,00,000 dividend. All relevant legal, accounting and approval requirements have been assessed. The simplified declaration entry is:
| Event | Account | Debit ₹ | Credit ₹ |
|---|---|---|---|
| Dividend declared | Retained earnings or approved distribution account | 1,00,000 | — |
| Dividend declared | Dividend payable | — | 1,00,000 |
| Separate bank funding | Dividend bank account | 1,00,000 | — |
| Separate bank funding | Operating bank | — | 1,00,000 |
Declaration creates the supported liability. Funding the separate bank moves money between company accounts and does not clear the shareholder obligation by itself.
Do not debit Dividend expense in operating costs simply because bank payment will occur. The distribution and its settlement should remain distinguishable from the company’s trading performance.
Payment without a deduction
If the full illustrative ₹1,00,000 is paid to entitled shareholders without any applicable deduction under the assessed facts, debit Dividend payable ₹1,00,000 and credit Dividend bank ₹1,00,000.
The liability closes when the supported payment is completed. A payment instruction that fails or is returned may leave an unpaid obligation and should not be treated as final settlement.
Maintain shareholder-wise detail so the control balance can be reconciled with individual entitlements, payments and unpaid amounts. A total bank debit alone cannot identify which shareholder remains unpaid.
Illustrative payment with withholding
Assume a separate assessed payment working requires withholding of ₹10,000 from the same gross ₹1,00,000 entitlement. The figures demonstrate accounting only and do not prescribe a tax rate or threshold.
Debit Dividend payable ₹1,00,000, credit Dividend bank ₹90,000 and credit Dividend withholding payable ₹10,000. The shareholder’s gross entitlement is settled through net payment plus the supported deduction.
When the ₹10,000 is remitted to the relevant authority, debit Withholding payable and credit the paying bank. Do not debit retained earnings again or recognise a new dividend expense at remittance.
Determine actual withholding obligations from the law and shareholder circumstances applicable to the payment. The journal cannot replace that assessment.
Dividends declared after the reporting date
ICAI AS 4 explains that a dividend declared after the balance-sheet date is not recognised as a liability at that earlier date unless a statute requires otherwise; the standard addresses disclosure of such dividends.
The declaration date therefore matters. Do not backdate the liability to 31 March merely because the dividend relates commercially to profits for the year ended then.
Keep the approved financial statements and later declaration documents connected. They explain why a distribution can be disclosed in one reporting package while the liability arises in a later accounting period.
Reconcile the separate bank and payable
The dividend-bank balance and Dividend payable may differ temporarily because of withholding, returned payments or other supported timing items. Prepare a reconciliation rather than assuming those two figures must always match exactly.
For each shareholder, show gross entitlement, deduction, net amount paid, date and unpaid balance. Match the payment references to bank records and investigate failed transfers promptly.
Any statutory treatment of unpaid or unclaimed dividends requires review under the applicable requirements. Do not release an old payable to income solely because a shareholder has not responded.
Avoid confusing other shareholder transactions
A repayment of a shareholder loan is not a dividend merely because profits exist. A share-capital transaction, director remuneration or expense reimbursement also needs its own legal and accounting analysis.
Likewise, an informal cash withdrawal by an owner-manager does not become a valid dividend retrospectively just by renaming its ledger. Obtain the actual authority and determine the correct treatment from the transaction facts.
Keep these balances separately identifiable. That makes both shareholder statements and financial reporting easier to review.
Close the distribution trail
Reconcile the declared amount with the approved working, shareholder detail, funded account, completed payments and withholding liabilities. Review any residual debit or credit balance for a specific explanation.
Keep shareholder identity changes traceable
A shareholder’s bank details or registered holding can change near declaration and payment. Use the approved entitlement basis and a controlled process for payment-detail changes, retaining evidence of who was entitled and where money was sent.
Do not redirect an unpaid dividend to another person merely because someone informally asks. Establish the valid authority and applicable requirements. This protects the company’s ability to show that its liability was settled to the correct entitled recipient, rather than merely proving that an equal amount left the bank.
The completed accounting should show when the company became obliged to distribute profits and how that obligation was settled. Preserving that distinction prevents a shareholder distribution from distorting operating expense and keeps unpaid entitlements visible.