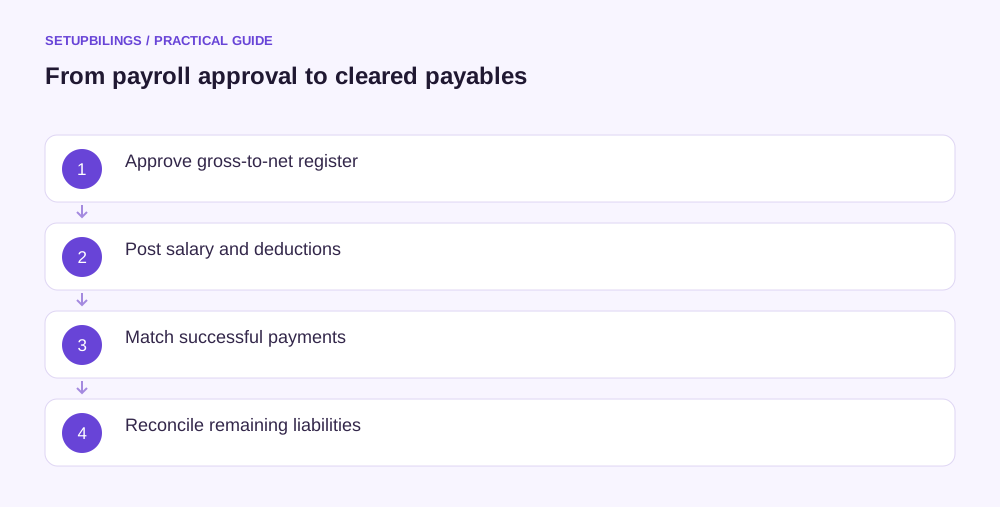
Recognise salary cost for employees’ services in the relevant period and record the unpaid obligation, even when bank payment will happen later. A payroll journal should distinguish gross salary, employee deductions, net salary payable and any separate employer costs. The later salary transfer clears the net payable instead of creating the expense again.
Start with an approved payroll register
The payroll register should explain employees included, service period, attendance adjustments, earnings, deductions and net amount due. Obtain approval before posting, while ensuring earned costs are not omitted simply because the payment run is delayed.
ICAI AS 15 addresses employee-benefit accounting and recognises a liability and related cost when employees provide service, subject to its requirements. Some employee costs may be included in an asset’s cost where another applicable standard requires or permits it. Ordinary salary expense is the simplified case illustrated here.
Do not use the total bank transfer as a substitute for the register. Net pay excludes amounts withheld from employees and may also contain reimbursements or advance recoveries that are not salary costs.
Illustrative gross-to-net entry
A Kanpur service business has an approved monthly gross salary total of ₹2,40,000. Its payroll working shows illustrative employee tax deductions of ₹12,000 and employee provident-fund deductions of ₹7,000, leaving net salaries of ₹2,21,000. These are assumed amounts, not prescribed rates or eligibility conclusions.
| Account | Debit ₹ | Credit ₹ |
|---|---|---|
| Salaries expense | 2,40,000 | — |
| Salary payable to employees | — | 2,21,000 |
| Employee tax deductions payable | — | 12,000 |
| Employee PF deductions payable | — | 7,000 |
| Total | 2,40,000 | 2,40,000 |
The ₹19,000 deducted from employees is still part of their gross salary in this example. It is owed to the relevant recipients rather than included in the net bank transfer to employees. Crediting only net salary would omit those liabilities.
When ₹2,21,000 is paid successfully, debit Salary payable and credit Bank ₹2,21,000. Salary expense remains ₹2,40,000 under the stated facts.
Record employer contributions separately
Assume the approved working also identifies ₹8,000 of employer contribution cost. Debit Employer contribution expense ₹8,000 and credit the appropriate contribution payable ₹8,000.
This amount is additional employer cost, not another deduction from the employees’ ₹2,21,000 net pay. Keep employee and employer portions identifiable even if they are eventually remitted together.
When the related contributions are paid, debit the corresponding payable accounts and credit bank. The same principle applies to supported tax-deduction remittances: payment clears the liability rather than debiting salaries again.
Actual coverage, contribution bases, rates, deduction rules and deadlines depend on the relevant law and employee circumstances. Use a verified payroll working for the real amounts; the journal example demonstrates only the accounting structure.
Salary advances are recoveries, not negative wages
If an employee previously received an advance, its authorised recovery normally reduces the amount now payable to that employee and credits the advance asset. It should not reduce gross salary expense unless the underlying earnings themselves changed.
For example, a supported ₹3,000 advance recovery within a payroll run shifts ₹3,000 from employee net payable to the advance account. Keep the original advance and recovery references linked.
Review the applicable authority for deductions and the employment terms. A bookkeeping entry can record an approved recovery, but it cannot create permission to deduct money from wages.
Reimbursements and salary are different components
An approved travel reimbursement paid in the salary bank file may already have been recognised as an expense claim payable. Clear that reimbursement payable when paying it; do not add the same amount again to salary expense.
A combined ₹2,30,000 bank file could contain salary, reimbursement and other supported settlements. Reconcile its components to the respective liabilities. The convenience of one transfer file should not erase the differences in the accounts.
Keep payroll and expense-claim references separate enough that an employee query can be resolved without rebuilding the entire month’s journal.
Failed transfers leave an unpaid balance
A bank file can be approved for the full amount while individual employee payments fail. Match successful payments and returned funds with the payroll list. Leave failed payments in Salary payable until they are successfully settled.
Do not mark every employee as paid merely because the bank debited the file total temporarily. A later reversal or rejection must restore the relevant liability if the employee has not received the money.
Use employee-level detail for unpaid salaries. A single control balance cannot show whether one employee is owed two months or several employees each have a small failed transfer.
Reconcile each liability at month end
Compare salary payable with unpaid employee amounts, tax deductions payable with deductions and remittances, and contribution payables with employee and employer schedules. Review opening balances, current additions, payments and closing amounts separately.
Investigate unusual negative balances, duplicate employees and payroll journals posted twice. Compare headcount changes with joiner and leaver records, while keeping sensitive personal details restricted to the supporting payroll records.
Correct payroll changes through the register
A late attendance correction or approved arrears amount should flow through a revised payroll working showing the affected employee, period and gross-to-net change. Post the resulting liability adjustment with a reference to that working instead of editing only the bank payment amount.
If a salary was overpaid, establish the supported recoverable balance and authorised recovery process. Do not reduce an unrelated employee’s payable to keep the total bank file unchanged. The control ledger may still balance while individual employee rights are wrong, so employee-level reconciliation remains necessary.
The correct salary journal preserves the difference between employees earning wages, deductions becoming payable and money being transferred. That separation gives a credible salary cost and makes every unpaid obligation visible.