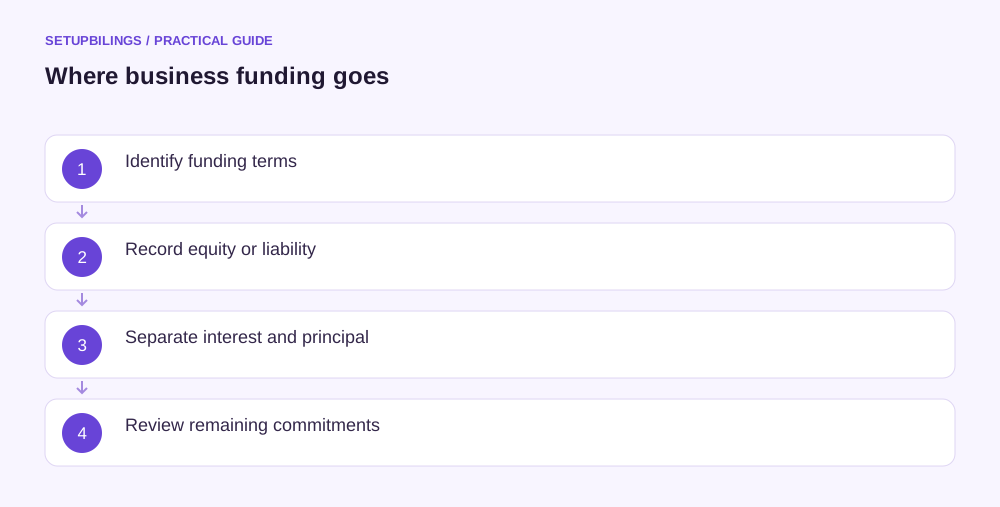
Owner’s equity is the residual interest in business assets after liabilities are deducted. A business loan creates a repayment obligation classified and measured under the applicable requirements. Both can fund the same purchase, but they appear differently in the accounts and create different future cash commitments.
The distinction is important when money comes from the owner or family. The sender’s identity alone does not establish whether a receipt is capital or a loan. The arrangement, documentation, legal form and applicable accounting requirements determine its treatment. A bank narration saying “fund transfer” cannot answer those questions.
Follow two sources into one business
Consider an illustrative Patna proprietor opening a small diagnostic equipment distribution business. The owner contributes ₹4,00,000 as capital and the business borrows ₹2,00,000 from a bank. Ignoring fees and tax, bank cash initially totals ₹6,00,000.
The balance sheet shows assets of ₹6,00,000, a loan liability of ₹2,00,000 and owner equity of ₹4,00,000. Neither receipt is customer sales. If all ₹6,00,000 were treated as revenue, the business would report income before supplying anything.
The proprietor uses ₹3,50,000 to acquire inventory and retains ₹2,50,000 in bank. Total assets still equal ₹6,00,000; their composition has changed. The funding distinction remains visible on the other side: ₹2,00,000 is owed to the lender, while ₹4,00,000 reflects the owner’s residual interest.
Equity changes through more than contributions
Suppose the business later earns ₹90,000 profit and the proprietor withdraws ₹40,000 for personal use. In a simplified capital reconciliation with no other changes, equity becomes ₹4,50,000: opening capital ₹4,00,000 plus profit ₹90,000 less drawings ₹40,000.
That does not mean ₹4,50,000 sits in bank. Equity is represented by the net resources remaining in the business, which may include stock, customer receivables, equipment and cash after liabilities. A business with positive equity can still lack cash for an immediate payment.
Losses reduce equity too. A business can have an unchanged capital contribution while accumulated losses reduce the owner’s recorded residual interest. Looking only at the amount initially introduced misses what happened after the contribution.
Loans require a settlement schedule
Borrowing creates commitments that should be tracked by principal, interest, repayment dates and other relevant terms. A monthly instalment often combines more than one component. Classifying the entire payment as an expense confuses financing repayment with the cost of borrowing.
Assume, illustratively, that a ₹12,000 instalment includes ₹9,500 principal and ₹2,500 interest. The principal portion reduces the loan liability. The interest is considered under the relevant expense or capitalisation requirements. Bank decreases by the full ₹12,000, so a cash forecast includes the entire payment.
Reconcile the loan ledger with lender statements. Differences may arise from unrecorded interest, charges, timing or an incorrect split. Do not force the ledger to the lender’s figure without identifying the component and period.
| Question | Equity funding | Ordinary loan funding |
|---|---|---|
| Does the initial receipt create sales revenue? | No | No |
| What does it represent? | Ownership interest | Repayment obligation |
| How is cash tracked? | Contribution and permitted withdrawal or distribution | Drawdown, interest and repayments |
| What supports classification? | Entity documents and contribution evidence | Loan terms and settlement evidence |
Actual instruments can be more complex than these ordinary examples. Preference shares, convertible arrangements and instruments with repayment features may need a detailed classification analysis rather than reliance on their names.
Record owner funding according to the entity
For a company, a shareholder’s transfer is not automatically share capital. Share allotment, loan documentation, approvals and applicable restrictions need to be considered. For a partnership, partner capital and current accounts may reflect the agreement and chosen accounting structure. A proprietor’s capital account should not be copied into those entities without adaptation.
If an owner expects repayment, document that expectation and the arrangement before the records become confused. If terms change, retain evidence of the change and assess its accounting consequences. Calling a loan “capital” because repayment has become inconvenient does not eliminate the obligation.
Related-party funding should also remain transparent. The relationship may affect required disclosures and users' assessment of the business. Avoid burying several people’s funding in one unexplained capital total.
Compare funding cost with the asset or activity being financed. A short loan used to support slow-moving stock may create repayment pressure before sales convert into cash. That mismatch is visible only when the owner sees both the loan schedule and the stock or customer collection cycle. Accounting classification does not decide whether borrowing is commercially sensible, but it supplies the separate balances and dates needed to assess the choice. Review those links before assuming a rising bank balance means expansion has become affordable.
Use funding information in decisions
Before buying additional stock, compare projected operating cash with loan repayments and other commitments. Equity funding may reduce scheduled debt repayments, but owners still need a return and sufficient resources for their own plans. Funding structure does not replace the need for a viable business margin.
A useful monthly funding report contains opening balances, new receipts, principal repayments, interest, owner contributions and withdrawals, plus closing balances. Link it to bank records and keep forecast movements separate from completed transactions.
Equity and loans explain where resources came from and who has claims against them. Record each receipt by its substance, track subsequent movements and separate financing from sales. The resulting accounts let the owner judge performance without mistaking borrowed cash for earnings or recorded equity for immediately spendable money.