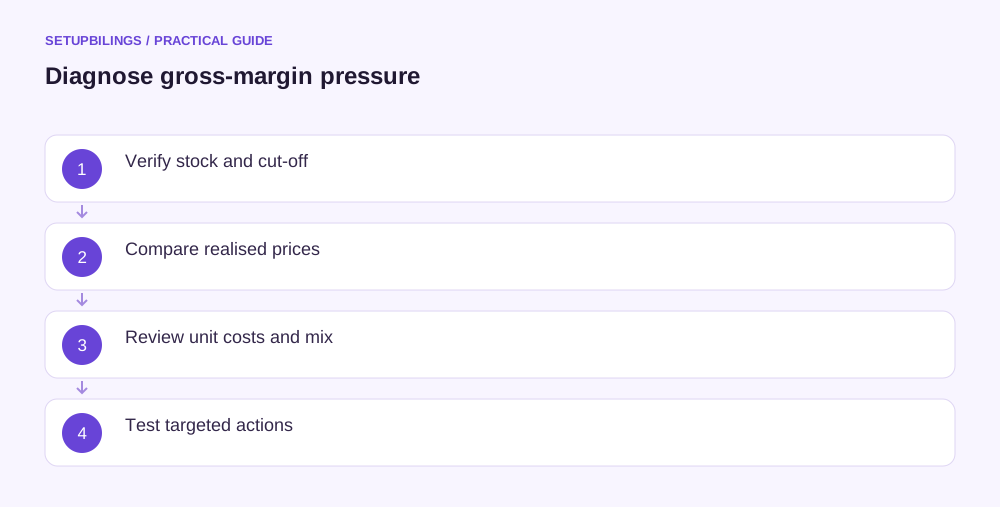
A falling gross margin means the business retains less gross profit from each rupee of revenue. It can indicate higher purchase or production costs, weaker selling prices, heavier discounts, a shift toward lower-margin products or changes in inventory accounting. Calculate the movement first, then separate these causes before taking action.
Gross margin = gross profit ÷ net revenue × 100. Gross profit is revenue less the cost of the goods or services included in the chosen gross-profit definition. Keep that definition consistent. A service firm that moves project salaries below gross profit can show an apparent improvement without earning any more money.
Confirm that the decline is real
Compare equivalent periods and use sales after relevant returns and discounts. Check whether revenue and costs are measured on a consistent tax basis. Investigate changes in freight classification, production overhead allocation or stock adjustments before interpreting the percentage commercially.
Read the inventory valuation working. Under ICAI AS 2, inventories within its scope are measured at the lower of cost and net realisable value, and cost includes relevant purchase and conversion components. A write-down can reduce current gross profit even when the affected goods were purchased earlier.
Also confirm stock quantities and transaction cut-off. Missing closing inventory understates profit; goods recorded as purchases before they are actually received can distort the period; sales recorded without the corresponding cost can overstate margin. A reliable diagnosis begins with reliable accounting.
Separate price pressure from cost pressure
An illustrative Indore metal-container trader sells 1,000 units in one month at ₹1,000 each. Unit cost is ₹700. Revenue is ₹10 lakh, cost of goods sold ₹7 lakh and gross profit ₹3 lakh, producing a 30% margin.
In the following month, the same quantity sells at the same price but unit cost rises to ₹760. Gross profit falls to ₹2.4 lakh and margin to 24%. The six-percentage-point decline is entirely cost-driven in this simplified comparison.
A selling price of ₹1,060 would recover the former ₹300 gross profit per unit, but it would not recover a 30% gross margin. A 30% margin at ₹760 cost requires price = ₹760 ÷ 0.70, approximately ₹1,085.71. This distinction matters when approving price revisions.
Do not confuse margin with markup
Markup expresses profit as a percentage of cost; margin expresses it as a percentage of sales. Buying at ₹760 and adding a 30% markup gives a selling price of ₹988, with profit of ₹228. The resulting margin is ₹228 ÷ ₹988, approximately 23.1%, rather than 30%.
State which measure a pricing sheet uses. A mistaken label can cause repeated underpricing even when every calculation is internally consistent. Review quotations, trade discounts and sales-team incentive rules for the same confusion.
When prices are negotiated customer by customer, analyse realised selling price after discounts rather than the printed price list. A list-price increase may fail to protect margin if sales staff compensate buyers with larger rebates.
Test whether sales mix explains the average
Consider a distributor selling premium and standard products. Premium goods generate a 40% gross margin; standard goods generate 20%. If each contributes ₹5 lakh sales, total gross profit is ₹3 lakh on ₹10 lakh revenue, or 30%.
If premium sales fall to ₹2 lakh and standard sales rise to ₹8 lakh, with unchanged category margins, total gross profit becomes ₹0.8 lakh + ₹1.6 lakh = ₹2.4 lakh. The overall margin falls to 24% even though neither category was discounted and neither cost changed.
| Possible cause | Evidence to examine |
|---|---|
| Higher unit input cost | Purchase price and freight records |
| Lower realised price | Invoice prices, discounts and rebates |
| Lower-margin mix | Product and customer sales shares |
| Returns or quality loss | Credit notes and rejection reports |
| Stock adjustment | Count differences and valuation workings |
This decomposition prevents a blanket price increase from targeting the wrong products. The business may instead need to improve availability or promotion of its premium range.
Investigate losses around the sale
Returns, damage, shortages and warranty commitments can weaken economics even when invoice margins appear stable. Link credit notes to the original product and customer. A returned item that can be resold differs from one that must be scrapped.
For manufacturers, examine yields, scrap, rework, overtime and capacity use. A purchase-price rise is only one possible cause. Low output can leave fixed production overhead unallocated under the relevant inventory principles rather than justifying higher inventory values to protect profit.
Separate a supplier rebate earned for the current period from a late credit relating to earlier purchases. Timing differences can create a temporary margin spike or decline that should be explained rather than treated as a new normal.
Review purchase commitments as well as historical costs. A supplier price increase may already be agreed but not yet visible in goods sold. Quotation validity periods and inventory replacement costs help the owner see whether today’s margin is likely to persist on the next purchase cycle.
Choose a targeted response
Create a bridge from previous gross profit to current gross profit, showing volume, selling-price, unit-cost, mix and identifiable stock effects. More detailed methods can allocate interaction effects differently, so label the method and avoid pretending every component is exact.
Then test actions at transaction level. Renegotiating freight, setting order minimums, revising discounts or reducing rework may be more effective than raising all prices. Quantify the expected rupee benefit and consider whether demand or customer retention will change.
A falling gross margin is an early signal, not a complete diagnosis. Finish the review with the specific products, costs or accounting adjustments responsible, the evidence supporting that conclusion and the next period’s measure that will show whether the action worked.