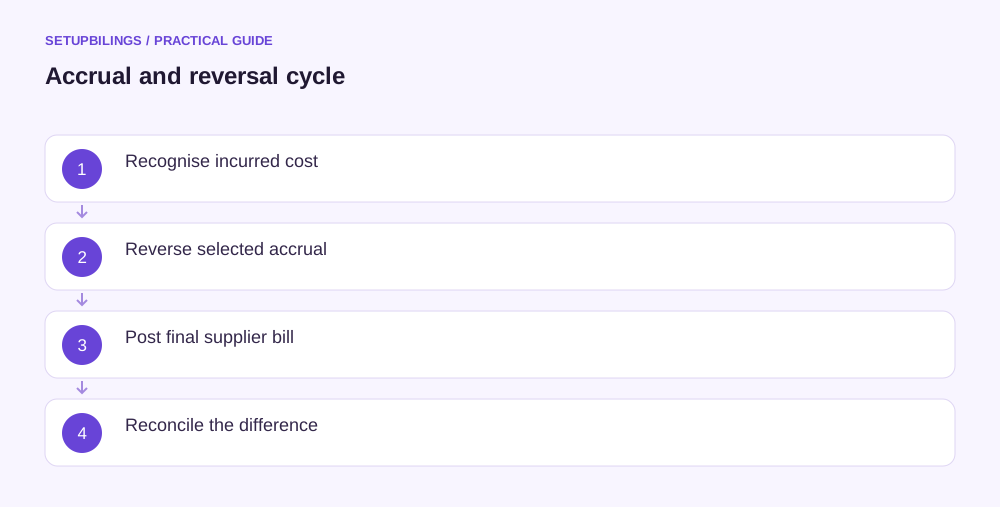
A reversing entry cancels a selected prior-period adjusting entry at the start of the next period so the ordinary transaction workflow can proceed without duplicating the adjustment. It is often useful for supported accruals that will soon be replaced by supplier bills or payroll records. Use it deliberately; not every closing balance should reverse automatically.
Understand the problem it solves
At month end, a business may recognise a cost already incurred before the invoice arrives. In the next month, the accounts team will enter the invoice through its usual expense workflow. Without a clearance or reversal, both entries can remain and overstate the cost and liability.
One solution clears the accrual directly against the final bill. Another reverses the accrual first and then records the bill normally. Both can work when applied consistently, but using both for the same estimate can create a second error.
AS 1’s accrual principle explains why the original adjustment belongs in the period of the incurred cost. The reversal is a processing technique for the next period; it does not erase that earlier period’s recognised cost.
Illustrative expense cycle
A Raipur business estimates March electricity cost at ₹12,500 from supported consumption. The bill arrives in April at ₹13,000 before any separate tax analysis. Assume the reversal method is chosen.
| Event | Account | Debit ₹ | Credit ₹ |
|---|---|---|---|
| March accrual | Electricity expense | 12,500 | — |
| March accrual | Accrued electricity payable | — | 12,500 |
| April reversal | Accrued electricity payable | 12,500 | — |
| April reversal | Electricity expense | — | 12,500 |
| April invoice | Electricity expense | 13,000 | — |
| April invoice | Supplier payable | — | 13,000 |
March carries ₹12,500 of cost. In April, the ₹13,000 invoice and ₹12,500 reversal leave a net ₹500 expense difference under the stated facts. The final supplier liability is ₹13,000 until paid.
The actual treatment of the difference depends on the evidence and applicable framework. A new estimate difference is not automatically a correction of an earlier error.
The temporary credit needs explanation
Immediately after the April reversal and before the bill is entered, Electricity expense may show a credit. That temporary balance is expected within this controlled cycle, but it can confuse interim reports.
Maintain a schedule of reversed accruals awaiting final bills. Review it before issuing management reports, especially where the bill arrives later than expected or the amount is material.
If the service remains unbilled at the next month end, reassess the required accrual rather than leaving the temporary reversal to understate cumulative costs indefinitely.
Select entries using their expected next step
A good reversal candidate has a clear original estimate, a linked upcoming transaction and an owner responsible for matching the final document. Routine unbilled services and some payroll accruals can fit that pattern.
A valid supplier invoice already recorded as payable should not usually be reversed merely because a new month began. The obligation continues until settlement or another supported event changes it.
Similarly, cash receipts, asset purchases and owner contributions are real transactions, not temporary estimates to cancel automatically. Review the substance rather than applying a reversal flag to every journal posted on the last day of the month.
Provisions and prepayments need their own process
A warranty provision may remain necessary across several periods and should be reviewed and used under the applicable standard. An automatic full reversal could remove a real obligation while claims are still expected.
A prepaid subscription represents future service benefit. Its normal release to expense follows the coverage schedule, rather than a blanket reversal of the original payment entry.
Depreciation is another cost allocation that ordinarily remains in the records. Reversing it at the next month’s start would undo the accumulated allocation unless a specific supported correction was intended.
Keep tax assumptions separate
The example deliberately excludes recoverable tax from the estimate. A financial accrual does not automatically satisfy the document and other conditions for input GST. The final invoice needs its own tax assessment.
If tax was included in a supported adjustment, the reversal must mirror the actual original components. Do not reverse only the expense while leaving an unexplained tax debit or liability behind.
The accounting reversal also does not automatically amend a filed return. Review any reporting consequences through the relevant process rather than assuming the journal handles them.
Prevent duplicate or missing reversals
Assign a unique link between the original accrual and its reversal. Confirm the reversal date, amount, accounts and approval before scheduling it. A reversal posted twice can create a false debit liability balance.
When the final invoice arrives, identify the original estimate in the bill working. Do not also debit the accrual liability if it has already been reversed in full.
For partial bills, track what remains unmatched. One invoice may replace only part of an estimate covering several services or suppliers.
Review the complete cycle
Reconcile opening accruals, reversals, final documents and new closing estimates. Investigate items repeatedly reversed and re-accrued without better evidence.
Match the reversal to the original components
A closing accrual may contain several expense categories or cost centres. Its reversal should mirror those supported components, not credit a single unrelated expense merely because the total agrees.
For example, reversing a combined warehouse-and-office utility accrual entirely against office expense would distort departmental reporting even if total company expense reconciled after the final bill. Keep the original allocation visible and review any change in the final invoice separately. Reversal is cancellation of the selected estimate, not an opportunity to move costs without explanation.
The reversal method is useful when it simplifies a known follow-up transaction while preserving the correct period cost. Its reliability comes from matching the whole cycle, not from the convenience of an automatic first-day journal.