Debit means the left side of an accounting account, and credit means the right side. They are labels for recording financial effects, not synonyms for payment and receipt. Whether a debit increases or decreases a balance depends on the account type. The same is true of a credit.
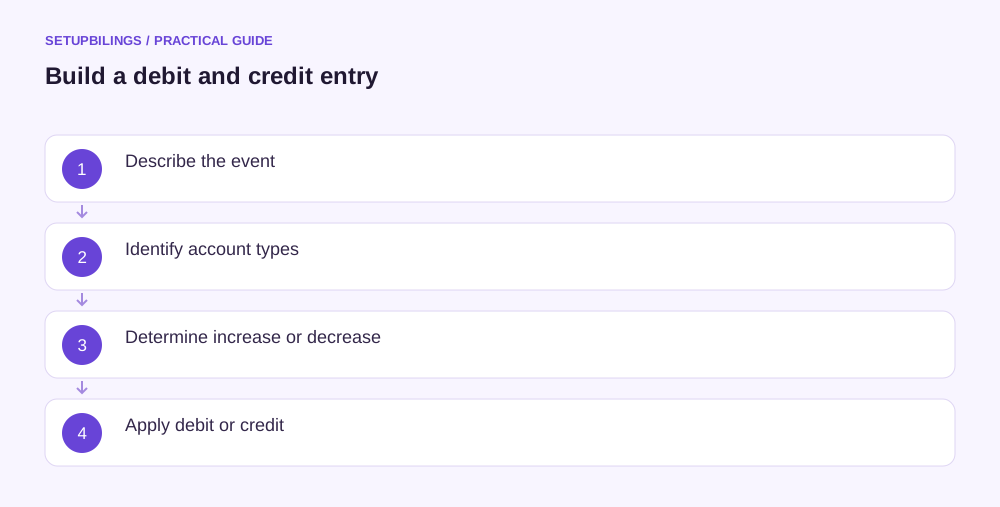
The easiest way to understand an entry is to describe the business event first. Identify what changed, classify the affected accounts and decide whether each balance increases or decreases. Only then apply the debit or credit label. This approach works better than guessing from the bank narration.
Learn the account-type pattern
Assets normally increase with debits and decrease with credits. Liabilities and equity normally increase with credits and decrease with debits. Expenses generally increase with debits, while income generally increases with credits. Special and contra accounts need attention because their balances can work against the main account they relate to.
| Account group | Usual increase | Usual decrease |
|---|---|---|
| Assets | Debit | Credit |
| Liabilities | Credit | Debit |
| Equity | Credit | Debit |
| Expenses | Debit | Credit |
| Income | Credit | Debit |
This pattern follows the accounting equation and the way income and expenses affect equity. It does not imply that all debit entries are beneficial or that credit entries are harmful. An expense can increase through a debit even though it reduces profit.
Start with a bank-funded purchase
Imagine an illustrative Guwahati stationery shop buying a printer for its own office use for ₹20,000. Assume it qualifies as equipment and tax is excluded. Equipment, an asset, increases by ₹20,000, so it is debited. Bank, another asset, decreases by ₹20,000, so it is credited.
The entry is debit equipment ₹20,000 and credit bank ₹20,000. Total debits equal total credits. The shop exchanged one asset for another; the payment did not automatically create a ₹20,000 operating expense.
Now suppose the same printer is bought for resale in the shop’s ordinary business. The debit account would be considered under inventory or purchase recording, depending on the system. The debit-and-credit pattern remains, but correct classification still requires knowing the item’s purpose.
Use supplier credit to see a liability
The shop receives resale goods worth ₹45,000 with payment due later. In a simplified perpetual inventory example, inventory is debited ₹45,000 because the asset increases. Supplier payable is credited ₹45,000 because the liability increases.
When ₹30,000 is paid, the supplier payable is debited and bank is credited. The payable falls to ₹15,000. The payment clears part of the existing liability; it is not a fresh purchase.
This distinction helps diagnose a common error. If the bank payment is debited to purchases again, the supplier balance remains open and the purchase is duplicated. An entry can balance perfectly while using the wrong debit account.
A customer sale creates income and a receivable
Suppose the shop supplies a business customer with goods for ₹12,000 on credit. The customer receivable is debited because an asset increases. Sales is credited because income increases. In a perpetual inventory system, the cost and stock reduction also need their corresponding balanced entries.
If the customer pays ₹12,000 next week, bank is debited and the receivable is credited. Sales is not credited again. The business has collected an amount already recorded as due.
An immediate cash or UPI sale may combine earning and collection on the same date. Even then, record the underlying sale correctly and reconcile settlement details. A bank receipt can differ from the customer sale because of fees, deductions or settlement timing, each requiring its own explanation.
Understand why the bank statement looks reversed
A bank statement may call money added to your account a credit. Your own business books generally debit the bank asset when it increases. These descriptions differ because the bank and your business are recording different sides of their relationship.
Do not copy the statement’s “debit” or “credit” label into your ledger without considering your business’s account. For your books, the useful question is whether your bank asset increased or decreased and what caused the movement.
Similarly, a supplier’s credit note may reduce the amount your business owes, but the full accounting entry depends on what the adjustment relates to. Document labels do not eliminate the need to identify the affected accounts.
Returns and corrections use the same logic in reverse where appropriate. If an earlier ₹5,000 expense was duplicated, the correcting entry should remove the duplicate effect through the approved process, with the counterpart reflecting the actual error. Do not assume that a credit to an expense is always income; it may simply reduce an expense previously overstated. Understanding the reason for the reversal is more useful than treating the sign as a new type of business activity.
Check an entry in four steps
First, state the event in plain language: “We paid an old supplier bill.” Second, identify the accounts: bank and supplier payable. Third, identify the movement: both decrease. Fourth, apply the pattern: debit payable, credit bank.
Add amounts, document references and a clear description. If several accounts are involved, confirm that total debits still equal total credits. An instalment combining principal, interest and charges may require more than two lines.
Finally, review whether the entry reflects the right transaction and period. Debit-credit equality checks structure, while invoices, contracts and reconciliations support accuracy. Once the account types are clear, the labels become a practical recording tool rather than a vocabulary test. The account’s purpose remains the anchor when a familiar label seems to point the other way.